Understanding Personal Finance: A Beginner's Guide
Understanding Personal Finance: A Beginner's Guide
Personal finance plays an important role in our everyday lives. Whether you want to save money, manage expenses, invest for the future, or prepare for unexpected situations, understanding basic financial concepts can help you make better decisions.
You do not need to be a financial expert to manage your money effectively. By learning a few fundamental principles, you can gradually improve your financial habits and work toward your goals.
What Is Personal Finance?
Personal finance refers to how individuals manage their money, including income, expenses, savings, investments, insurance, and debt.
It involves making financial decisions based on your income, lifestyle, responsibilities, and future objectives.
For example, deciding how much of your monthly salary to save, whether to repay a loan early, and how to prepare for retirement are all aspects of personal finance.
1. Understand Your Income and Expenses
The first step toward financial stability is understanding how much money you earn and spend.
Start by identifying your income sources, such as salary, business income, freelance work, or investment returns.
Next, categorize your expenses into two groups:
Essential expenses: Rent, groceries, utilities, transportation, and loan payments.
Discretionary expenses: Entertainment, shopping, dining out, and subscriptions.
Tracking these expenses helps you identify spending patterns and areas where you could save money.
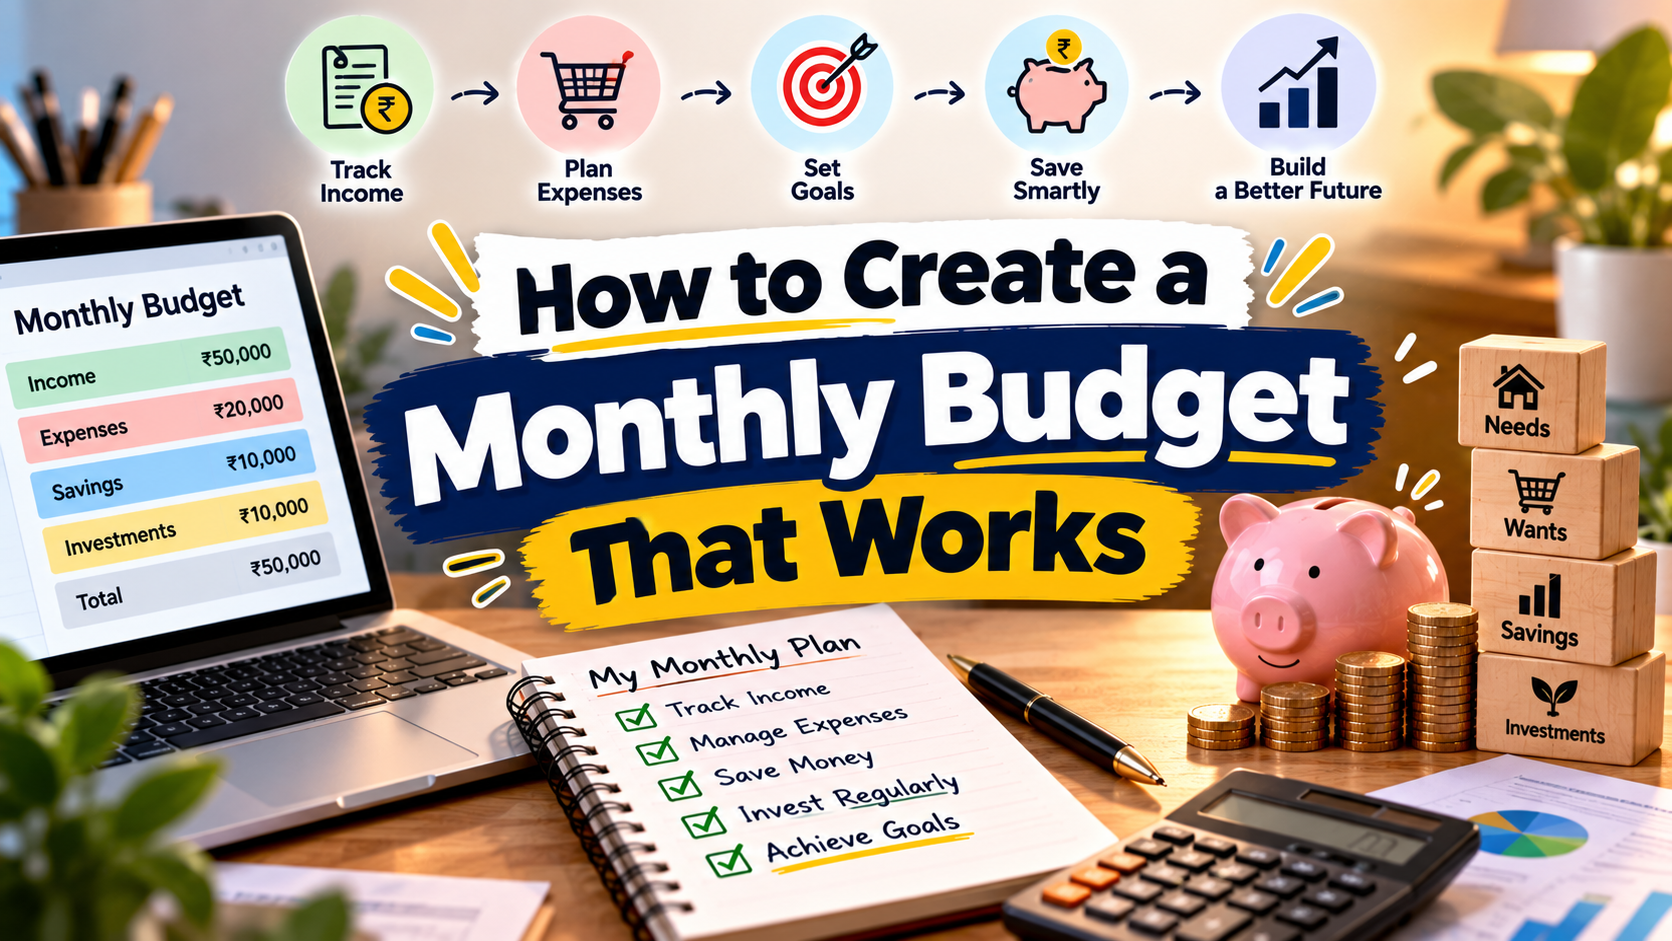
2. Create a Monthly Budget
A budget helps you allocate your income toward different financial priorities.
One commonly discussed budgeting approach is the 50/30/20 rule:
50% of income for needs.
30% for wants.
20% for savings and debt repayment.
These percentages are only a starting point. Your actual budget may need to differ depending on your income, location, family responsibilities, and financial goals.
The most important thing is to create a realistic budget that you can follow consistently.
3. Build an Emergency Fund
Unexpected expenses can arise at any time. Medical bills, urgent repairs, or temporary income loss can put pressure on your finances.
An emergency fund provides money for such situations without forcing you to rely on expensive borrowing or withdraw long-term investments at an unfavorable time.
A common goal is to save three to six months of essential living expenses. However, the appropriate amount depends on your employment stability, dependents, insurance coverage, and other circumstances.
Keep emergency savings accessible and separate from money intended for long-term investment.
4. Understand Saving and Investing
Saving and investing serve different purposes.
Saving generally focuses on preserving money and keeping it available for short-term needs. Investing involves putting money into assets with the expectation of earning returns over time.
Savings accounts and other suitable low-risk savings products may help with short-term goals, while investments such as mutual funds, shares, and bonds may be considered for longer-term objectives.
Investments carry different levels of risk, and returns are not guaranteed.
Before investing, consider your financial goals, time horizon, liquidity requirements, and ability to tolerate losses.
5. Manage Debt Responsibly
Borrowing can help finance important purchases, but excessive debt can restrict your financial flexibility.
Understand your loan interest rates, repayment schedules, fees, and outstanding balances.
Prioritize high-interest debt where practical while maintaining essential expenses and minimum payments on other obligations.
Avoid taking on new debt without understanding whether you can comfortably afford the repayments.
6. Set Clear Financial Goals
Financial goals give your money a purpose.
Examples include:
Building an emergency fund.
Saving for a home.
Funding higher education.
Planning for retirement.
Paying off outstanding loans.
Set a target amount and deadline for each goal. Then calculate how much you need to save regularly to make progress.
Review your goals periodically as your income, expenses, and priorities change.
Conclusion
Personal finance begins with understanding your money and making deliberate financial decisions.
By tracking expenses, creating a budget, building emergency savings, managing debt, and setting clear goals, you can establish healthier financial habits.
Disclaimer: This article is for educational purposes only and should not be considered personalized financial advice.