Understanding Credit Scores and How to Improve Them
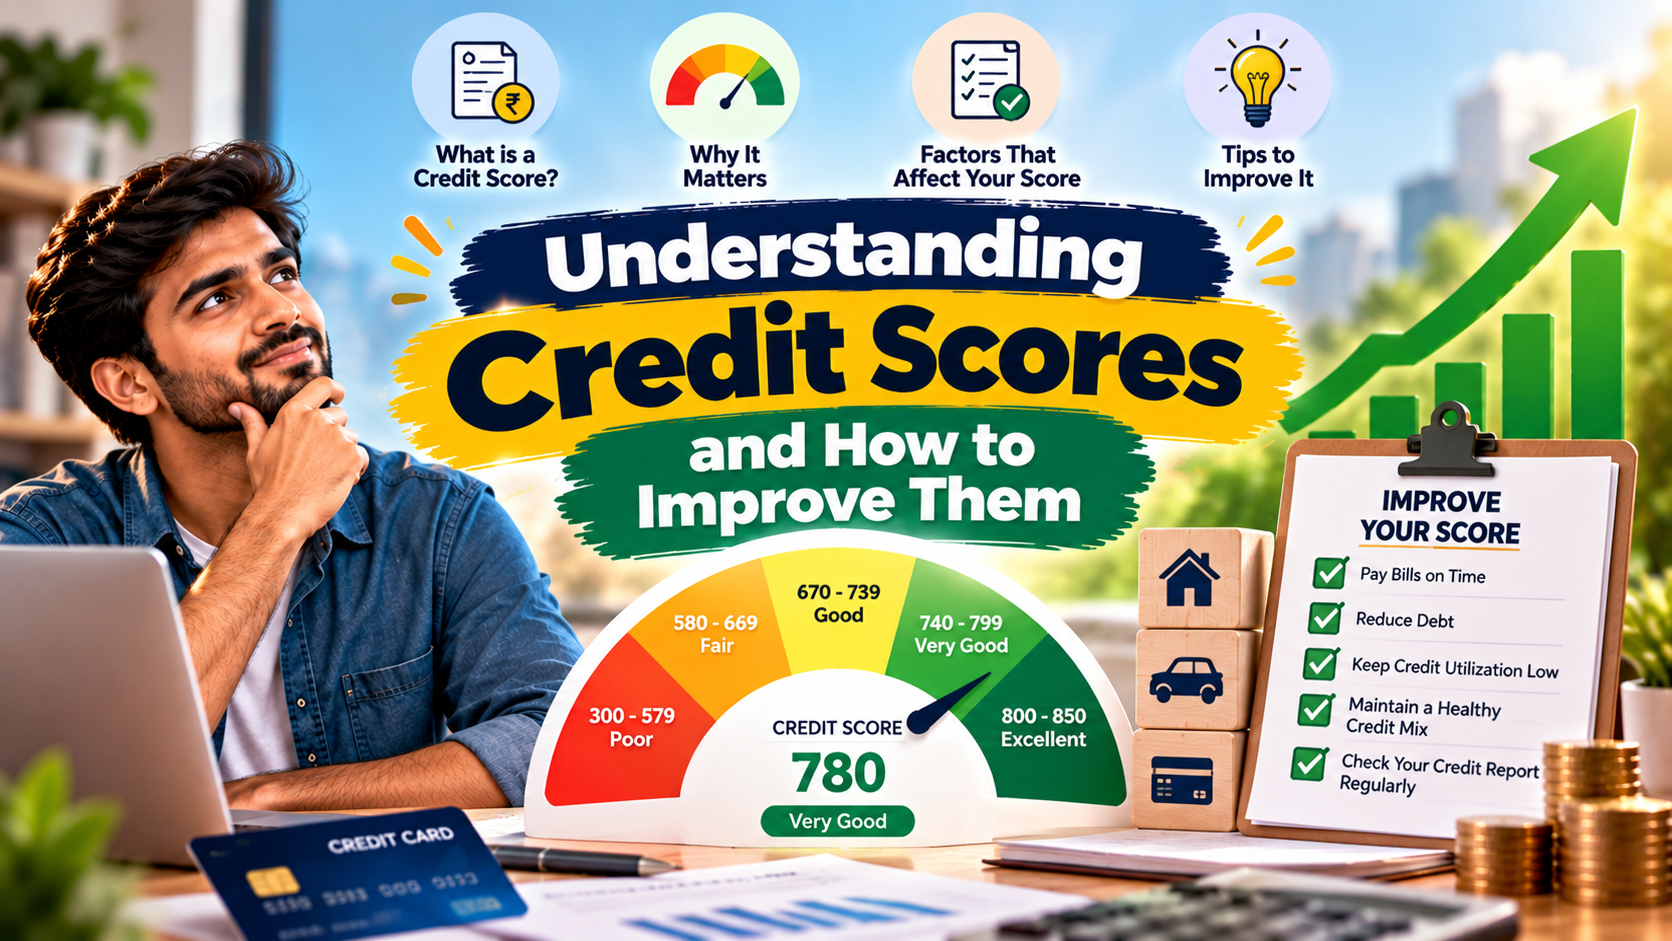
Understanding Credit Scores and How to Improve Them
A credit score is an important part of your financial profile.
Lenders may use credit scores and other information when evaluating applications for loans, credit cards, and other credit products.
Understanding your credit score can help you develop responsible borrowing habits and identify potential issues in your credit history.
What Is a Credit Score?
A credit score is a numerical indicator derived from information in your credit history.
In India, credit information companies calculate credit scores using their respective models and available credit information.
Different credit bureaus may use different scoring models and information, so scores are not necessarily identical across providers.
A credit score is one factor lenders may consider. It does not guarantee approval or rejection of a credit application.
Why Does Your Credit Score Matter?
Lenders may use your credit score alongside factors such as income, existing debt, employment information, and repayment capacity.
A stronger credit profile may improve your chances of qualifying for certain credit products or receiving more favorable terms.
However, lending decisions vary by institution and product.
Factors That Can Influence Your Credit Profile
1. Payment History
Repaying loans and credit card bills on time is important.
Missed or delayed payments may negatively affect your credit history.
Consider using payment reminders or automatic payments where appropriate, while ensuring that sufficient funds are available.
2. Credit Utilization
Credit utilization refers to the amount of revolving credit you use compared with your available credit limit.
For example, if your credit card limit is ₹1,00,000 and your outstanding balance is ₹30,000, your utilization is 30%.
Lower utilization is generally preferable to consistently using most of your available limit, although the impact depends on the scoring model and other factors.
3. Length of Credit History
The age of your credit accounts and the duration of your borrowing history may influence some credit scoring models.
Responsible management of existing accounts can help maintain a stable credit profile.
4. Credit Applications
Applying for several credit products in a short period may lead to multiple hard inquiries, depending on the lender and application process.
Frequent applications can be a concern to some lenders.
Apply for credit when you have a genuine need and have reviewed the terms.
5. Credit Mix
Your credit profile may include different types of credit, such as secured loans and unsecured credit.
However, you should not take out unnecessary loans simply to create a particular credit mix.
Borrow responsibly based on your financial needs.
Practical Steps to Maintain a Healthy Credit Profile
Pay loan EMIs and credit card bills on time.
Avoid using most of your available credit limit consistently.
Review your credit report periodically.
Dispute inaccurate information through the appropriate credit bureau process.
Avoid unnecessary credit applications.
Borrow only amounts you can reasonably repay.
Monitor accounts for unfamiliar activity.
How Long Does It Take to Improve a Credit Score?
There is no universal timeline.
Improvements depend on your existing credit history, the type of information affecting your score, the frequency of updates, and the scoring model used.
Consistent repayment habits can help improve your credit profile over time, but results are not guaranteed.
Conclusion
A credit score provides information about your credit history, but it is only one part of your overall financial profile.
Responsible borrowing, timely payments, and regular credit report reviews can help you maintain a healthier credit history.