Short-Term vs. Long-Term Savings Goals
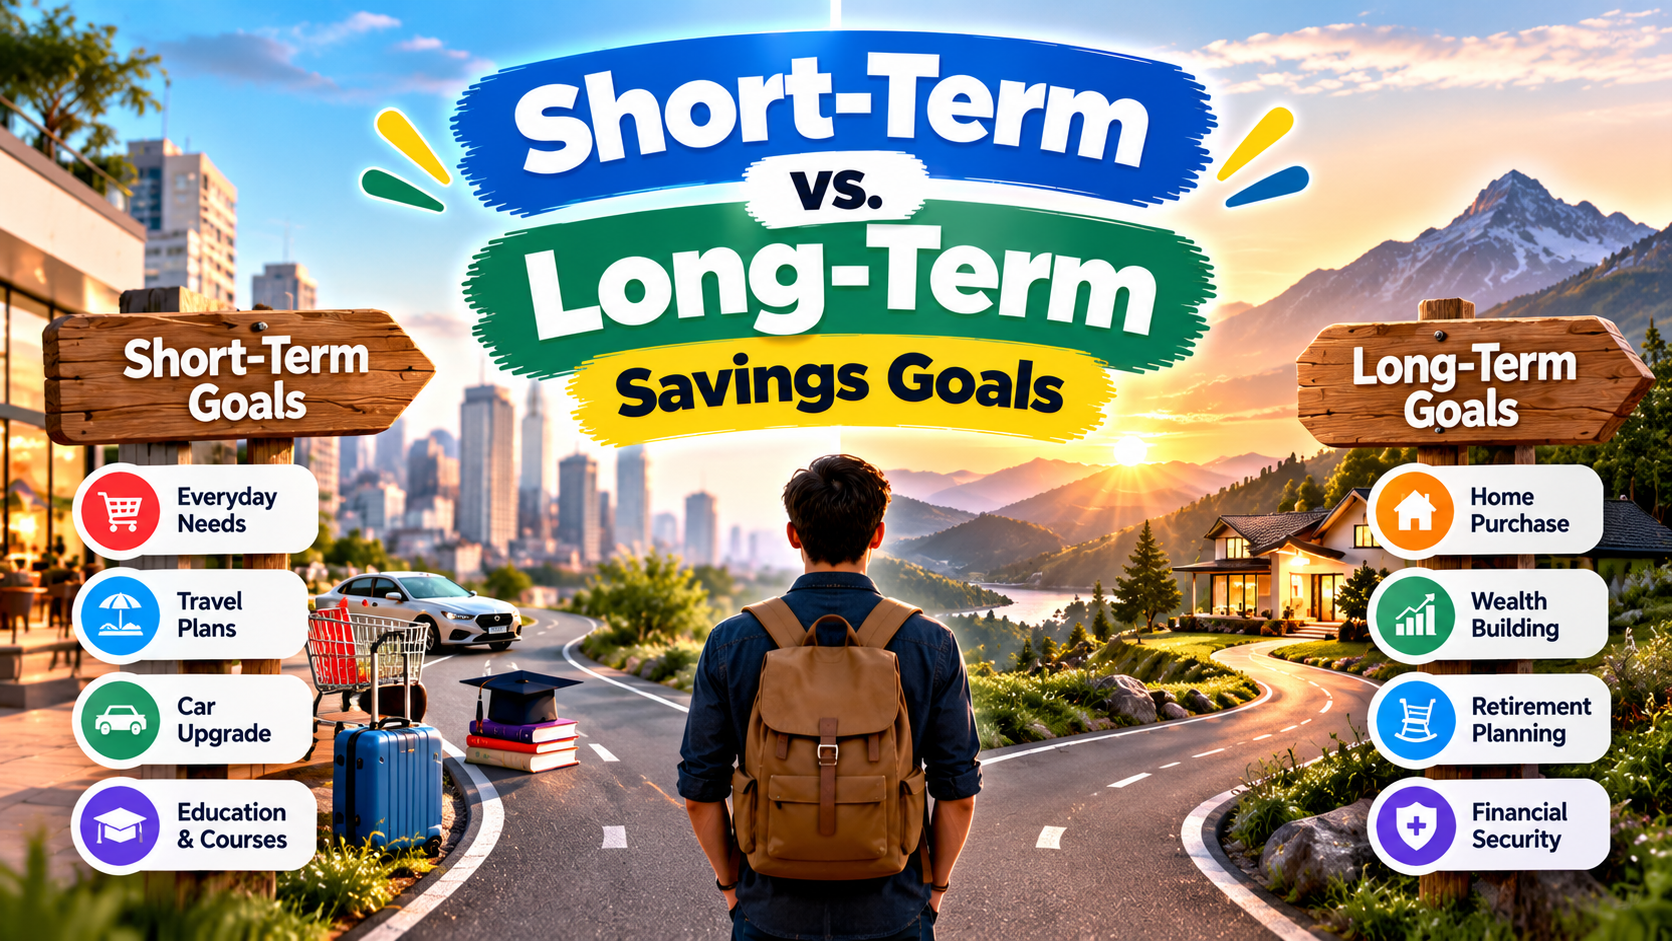
Short-Term vs. Long-Term Savings Goals
Saving money becomes easier to organize when each amount has a clear purpose.
Some goals require money within a few months, while others may be several years away.
Understanding the difference between short-term and long-term goals can help you choose suitable savings and investment approaches.
What Are Short-Term Savings Goals?
Short-term goals are financial objectives you expect to achieve relatively soon, often within the next one to three years.
Examples include:
Building an emergency fund.
Paying for a planned vacation.
Buying essential household equipment.
Preparing for an upcoming education expense.
Saving for a vehicle down payment.
Because the money may be needed soon, preserving the required amount and maintaining access to it are often important considerations.
What Are Long-Term Savings Goals?
Long-term goals generally have a longer timeline, often extending beyond five years.
Examples include:
Retirement planning.
Funding a child's future education.
Accumulating money for a home purchase.
Building long-term wealth.
Preparing for major future expenses.
Depending on the goal and your risk tolerance, long-term plans may involve a combination of savings and investments.
However, a long time horizon does not eliminate investment risk.
Short-Term vs. Long-Term Goals
Factor | Short-Term Goals | Long-Term Goals |
|---|---|---|
Time horizon | Usually within a few years | Often five years or longer |
Main priority | Access and preservation | Meeting future objectives |
Risk tolerance | Often relatively low | Depends on the goal and circumstances |
Common approaches | Suitable savings accounts and short-term deposits | Savings combined with suitable long-term investments |
Review frequency | As the target date approaches | Periodically over the investment horizon |
Main consideration | Having enough money when needed | Balancing growth, risk, and future purchasing power |
These are general guidelines, not rigid definitions.
Step 1: Define Each Goal
Write down what you are saving for and when you expect to need the money.
For example:
Emergency fund: ₹1,00,000 within 12 months.
Holiday: ₹60,000 within 10 months.
Education: ₹5,00,000 over five years.
Clear goals make it easier to estimate the amount you need to save regularly.
Step 2: Calculate Your Required Contributions
A simple way to estimate monthly savings is:
Monthly savings required = (Target amount − Current savings) / Months remaining
Suppose you want to save ₹60,000 over 12 months and already have ₹12,000 set aside.
Your remaining target is ₹48,000.
You would need to save ₹4,000 per month, ignoring interest and any fees.
This calculation can help you determine whether your goal fits your current budget.
Step 3: Consider Inflation
Inflation reduces the purchasing power of money over time.
For long-term goals, the amount you need in the future may be higher than today's equivalent cost.
For example, education or housing expenses may rise over several years.
Consider inflation when estimating long-term targets, while recognizing that actual price increases can differ from assumptions.
Step 4: Choose an Appropriate Place for Your Money
Your savings approach should reflect when you need the money and how much risk you can tolerate.
For short-term goals, prioritize access and the ability to meet the target when due.
For long-term goals, you may evaluate investment options that offer growth potential, while carefully considering volatility, costs, and the possibility of losses.
Avoid taking more risk simply because a goal is far away.
Step 5: Review Your Progress
Track your contributions and compare your current balance with the amount needed to reach your target.
If your income changes or an expense increases, adjust your contributions or timeline.
Review your assumptions periodically rather than waiting until the deadline approaches.
Conclusion
Short-term and long-term savings goals serve different purposes.
By defining your goals, estimating the required contributions, considering inflation, and selecting appropriate financial products, you can create a more organized savings plan.
Disclaimer: This article provides general educational information and does not recommend any particular financial product.