How to Set Financial Goals and Create an Action Plan
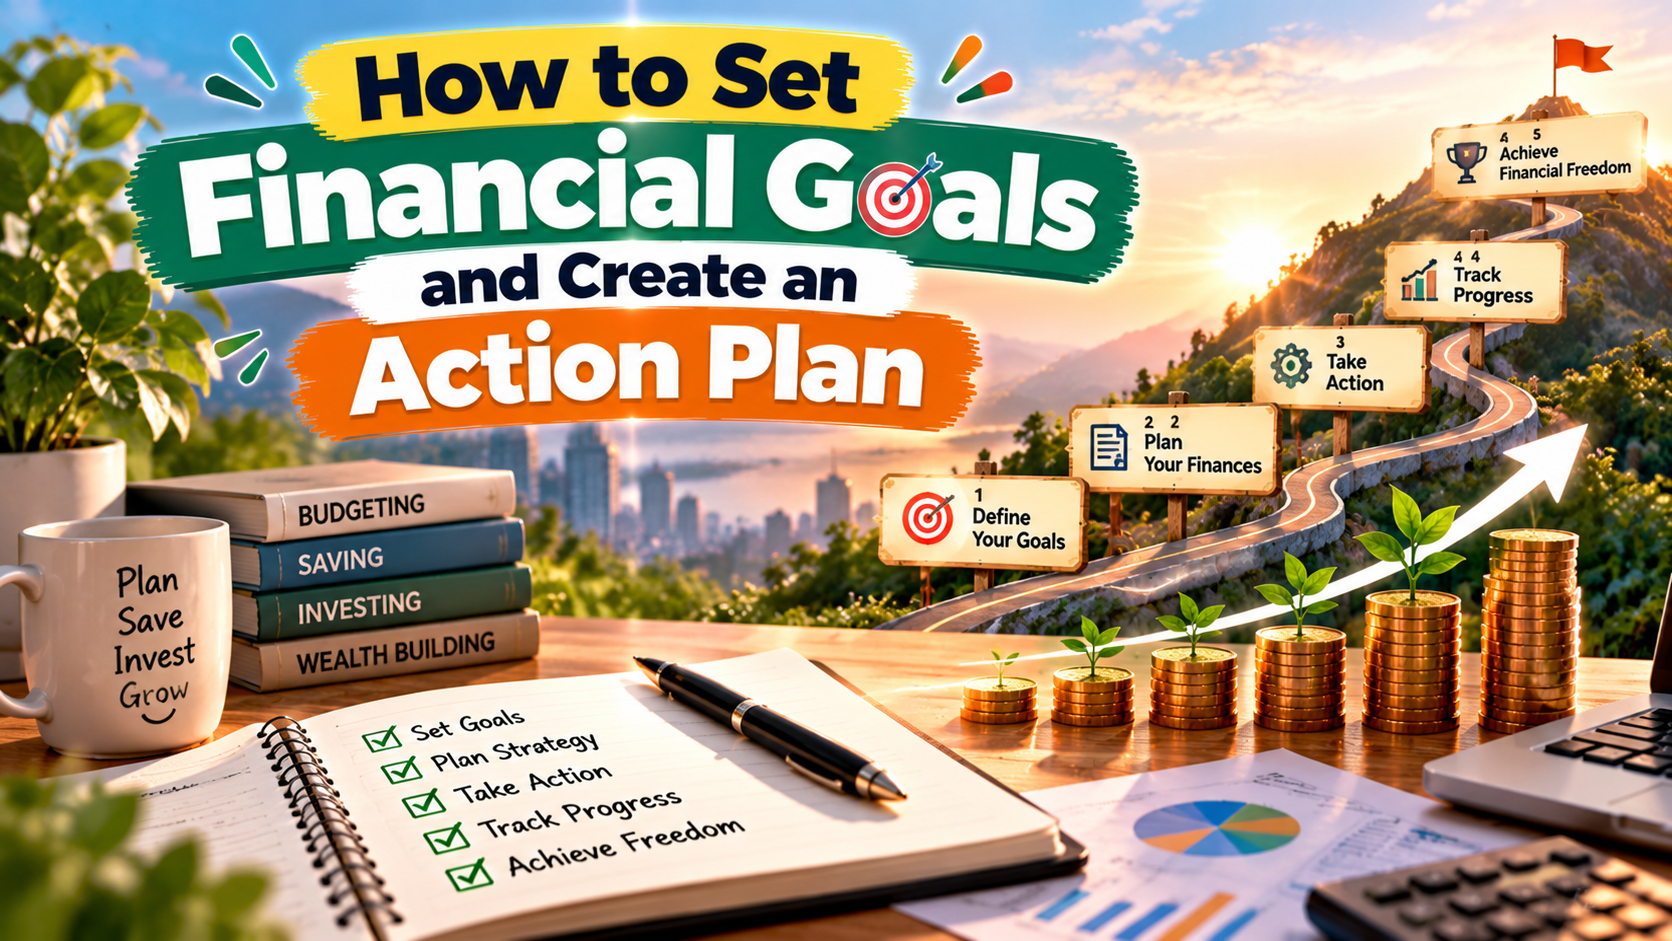
How to Set Financial Goals and Create an Action Plan
Financial goals help you decide how to use your money today to support your needs and priorities in the future.
Without clear goals, it can be difficult to decide how much to save, how much risk to take, or which expenses to prioritize.
A structured action plan can make your financial objectives easier to measure and manage.
What Are Financial Goals?
Financial goals are specific outcomes you want to achieve using your financial resources.
Common examples include:
Paying off debt.
Building an emergency fund.
Saving for a home.
Funding higher education.
Preparing for retirement.
Building long-term investments.
Goals can be short-term, medium-term, or long-term depending on the amount required and the date by which you need the money.
Step 1: Identify Your Priorities
Begin by listing the financial outcomes that matter most to you.
You may have several goals, but not all of them can necessarily receive equal priority.
For example, building an emergency fund and meeting essential expenses may take precedence over saving for a discretionary purchase.
Consider your current obligations, income, debt, and future responsibilities when deciding which goals should come first.
Step 2: Make Each Goal Measurable
A useful financial goal identifies what you want to achieve, how much money you need, and when you need it.
Instead of saying, "I want to save more money," define a specific target.
For example:
"I want to save ₹1,20,000 for an emergency fund over the next 12 months."
This gives you a target that can be measured and reviewed.
Step 3: Calculate Your Monthly Contribution
A simple starting formula is:
Monthly contribution = (Target amount − Current savings) / Months remaining
Suppose you want to save ₹1,20,000 over 12 months and have already saved ₹24,000.
Your remaining target is ₹96,000.
You would need to contribute ₹8,000 per month, ignoring interest and other changes.
If this amount is not affordable, consider extending the deadline, reducing discretionary expenses, or adjusting the target where appropriate.
Step 4: Create a Budget
Review your income and expenses to determine how much money you can allocate toward each goal.
Separate essential spending from discretionary expenses and identify opportunities to reduce unnecessary costs.
A budget can help you understand whether your goals are realistic given your current financial circumstances.
Step 5: Match Your Financial Approach to the Goal
The financial products you consider should reflect the time available and the level of risk you can tolerate.
For goals with a short deadline, preserving the required amount and maintaining access to the money may be particularly important.
For longer-term goals, suitable investments may help you pursue growth, but their values can fluctuate and losses are possible.
Do not rely on uncertain investment returns to meet an essential financial obligation.
Step 6: Automate Your Contributions
Where practical, arrange automatic transfers into designated savings or investment accounts.
Automation can make contributions more consistent and reduce the temptation to spend money that was intended for a goal.
Ensure that automated transfers do not leave you without enough money for essential expenses or required payments.
Step 7: Track Your Progress
Review your goals periodically.
For each goal, record:
Target amount.
Current balance.
Amount contributed.
Remaining amount.
Target date.
Monthly contribution required.
If your income or expenses change, update your plan accordingly.
Progress reviews help you identify problems early and make necessary adjustments.
Step 8: Reassess Your Goals When Life Changes
Financial plans should adapt to significant changes in your circumstances.
A new job, family responsibilities, increased living costs, or changes in your long-term priorities may require you to adjust your goals.
Review your plan at regular intervals and whenever a major change occurs.
Conclusion
Financial goals turn broad ambitions into measurable actions.
By defining clear targets, calculating required contributions, creating a realistic budget, and tracking progress, you can develop a more organized approach to managing your money.
Disclaimer: This article provides general educational information and should not be considered personalized financial advice.