How to Build a Diversified Investment Portfolio
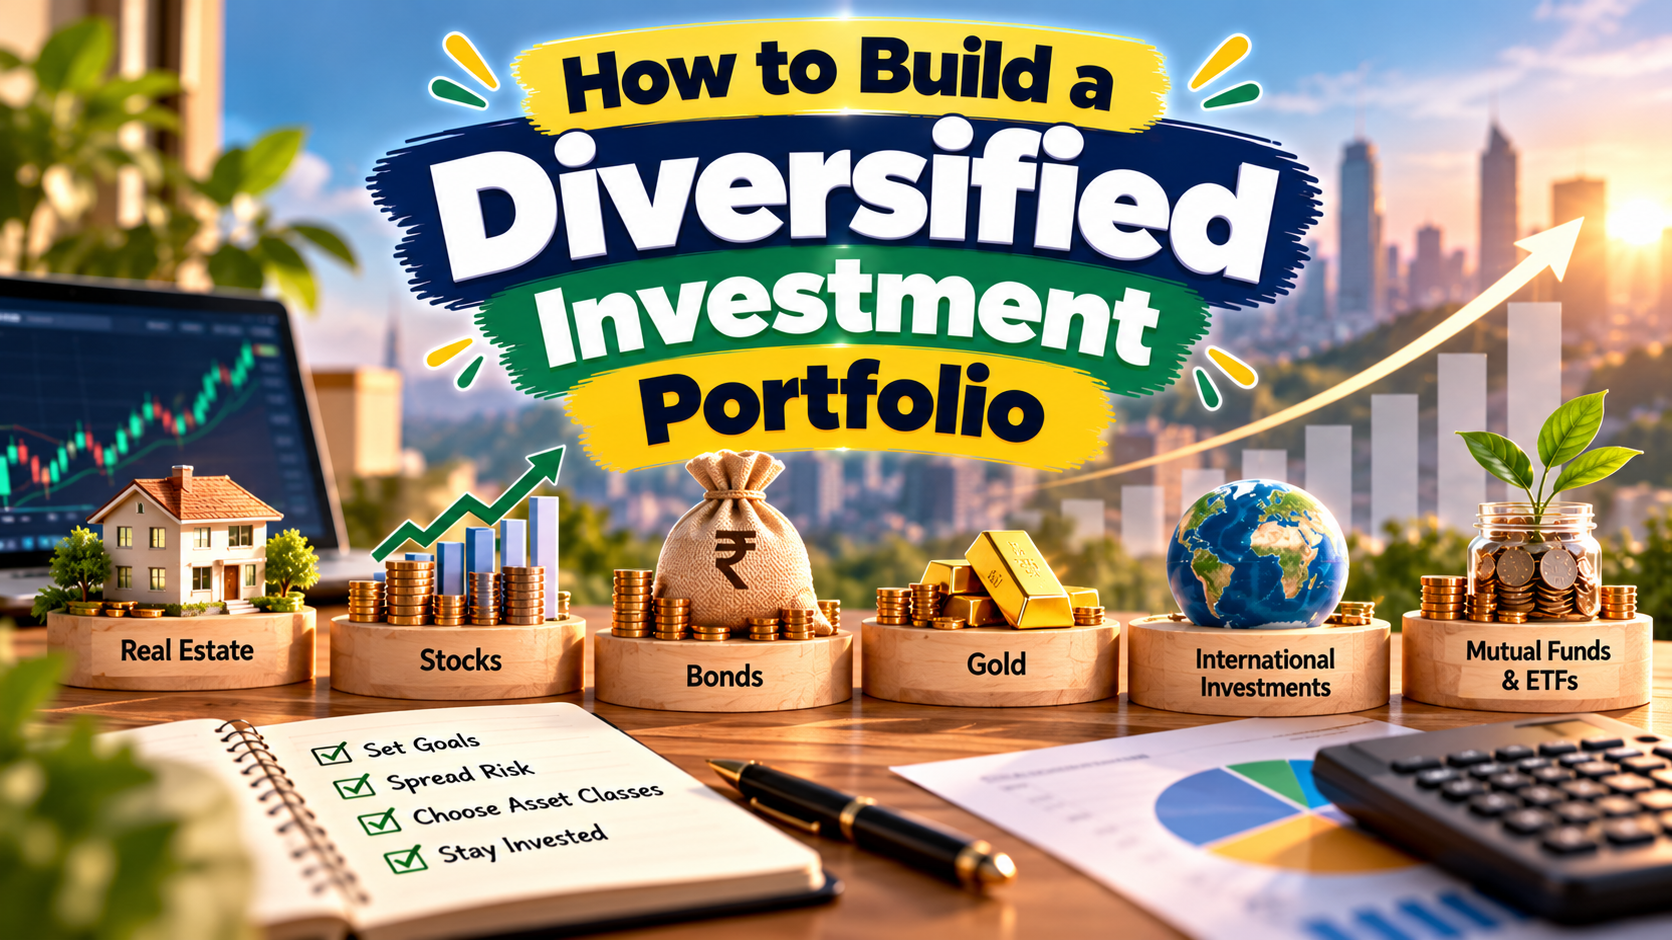
How to Build a Diversified Investment Portfolio
Investing all your money in a single stock, company, or asset class can expose your financial future to concentrated risk.
Diversification is a strategy for spreading investments across different assets, sectors, issuers, or markets.
Its purpose is to reduce dependence on any single investment or source of risk.
Although diversification can help manage risk, it cannot eliminate losses or guarantee positive returns.
What Is Portfolio Diversification?
Portfolio diversification involves holding investments that do not all depend on the same underlying factors.
For example, a portfolio may include equity funds, debt instruments, and cash or cash equivalents, depending on the investor's objectives.
The idea is that different investments may respond differently to economic conditions and market developments.
However, assets that appear different can still decline at the same time, particularly during periods of financial stress.
Why Is Diversification Important?
1. Reduces Concentration Risk
When too much of your portfolio is invested in one company or sector, an unfavorable development affecting that investment can have a disproportionate impact.
Spreading investments across suitable holdings can reduce this dependence.
2. Provides Exposure to Different Assets
Different asset classes have different characteristics.
Equities may provide growth potential but can be volatile. Debt instruments may provide interest income but can face credit and interest-rate risks.
Cash and cash equivalents can support liquidity needs but may not keep pace with inflation over long periods.
The role of each asset depends on your financial plan.
3. Supports Goal-Based Investing
Different goals may require different investment allocations.
For example, a retirement portfolio may have a different time horizon and risk profile from money intended for a home purchase in two years.
Separating investments by goal can help prevent short-term needs from being exposed to unsuitable risks.
Step 1: Define Your Financial Goals
Before selecting investments, identify what you want to achieve.
Examples include retirement, education, home ownership, or long-term wealth accumulation.
For each goal, estimate the target amount, timeline, and flexibility of the deadline.
Step 2: Assess Your Risk Tolerance and Capacity
Risk tolerance refers to how comfortable you are with investment fluctuations and potential losses.
Risk capacity refers to your financial ability to withstand those losses without jeopardizing important goals.
These are related but different concepts.
Someone may be emotionally comfortable with market volatility but have limited financial capacity to take risks because the money is needed soon.
Both factors should influence your investment decisions.
Step 3: Understand Asset Allocation
Asset allocation determines how investments are distributed across asset classes.
For example, a hypothetical portfolio might contain:
Asset Class | Illustrative Allocation |
|---|---|
Equity investments | 50% |
Debt investments | 40% |
Cash and cash equivalents | 10% |
Total | 100% |
This is an educational example, not a recommended allocation.
The appropriate allocation depends on the investor's financial objectives, investment horizon, risk capacity, and the characteristics of the products involved.
Step 4: Diversify Within Each Asset Class
Diversification should not stop at choosing several asset classes.
For equity investments, consider exposure across companies, sectors, and markets.
For debt investments, consider issuer quality, maturity, credit risk, and interest-rate sensitivity.
Owning several funds does not necessarily provide meaningful diversification if those funds hold many of the same underlying securities.
Step 5: Review Costs and Taxes
Investment fees and taxes can affect net returns.
Consider expense ratios, brokerage, transaction charges, exit loads, and the tax treatment applicable to your holdings.
The cheapest product is not always the most suitable, but costs should be understood before investing.
Step 6: Rebalance When Necessary
Over time, market movements can change your portfolio's asset allocation.
Suppose your target allocation is 50% equity and 50% debt. If equity performs much better, your portfolio may become more heavily weighted toward equity.
Rebalancing involves adjusting holdings or directing new contributions to bring the portfolio closer to its intended allocation.
The appropriate frequency and method depend on your strategy, transaction costs, taxes, and investment objectives.
Common Diversification Mistakes
Holding too much money in a single company.
Assuming several funds always mean adequate diversification.
Investing in assets you do not understand.
Taking unnecessary risks to chase higher returns.
Ignoring investment costs.
Failing to review changes in financial goals.
Conclusion
Diversification is an important tool for managing portfolio concentration risk.
By defining financial goals, evaluating risk capacity, selecting suitable asset classes, and reviewing your portfolio periodically, you can develop a more structured investment approach.
Disclaimer: This article is for educational purposes only and does not constitute personalized investment advice.