SIP vs. Lump-Sum Investing: Which Approach Should You Understand?
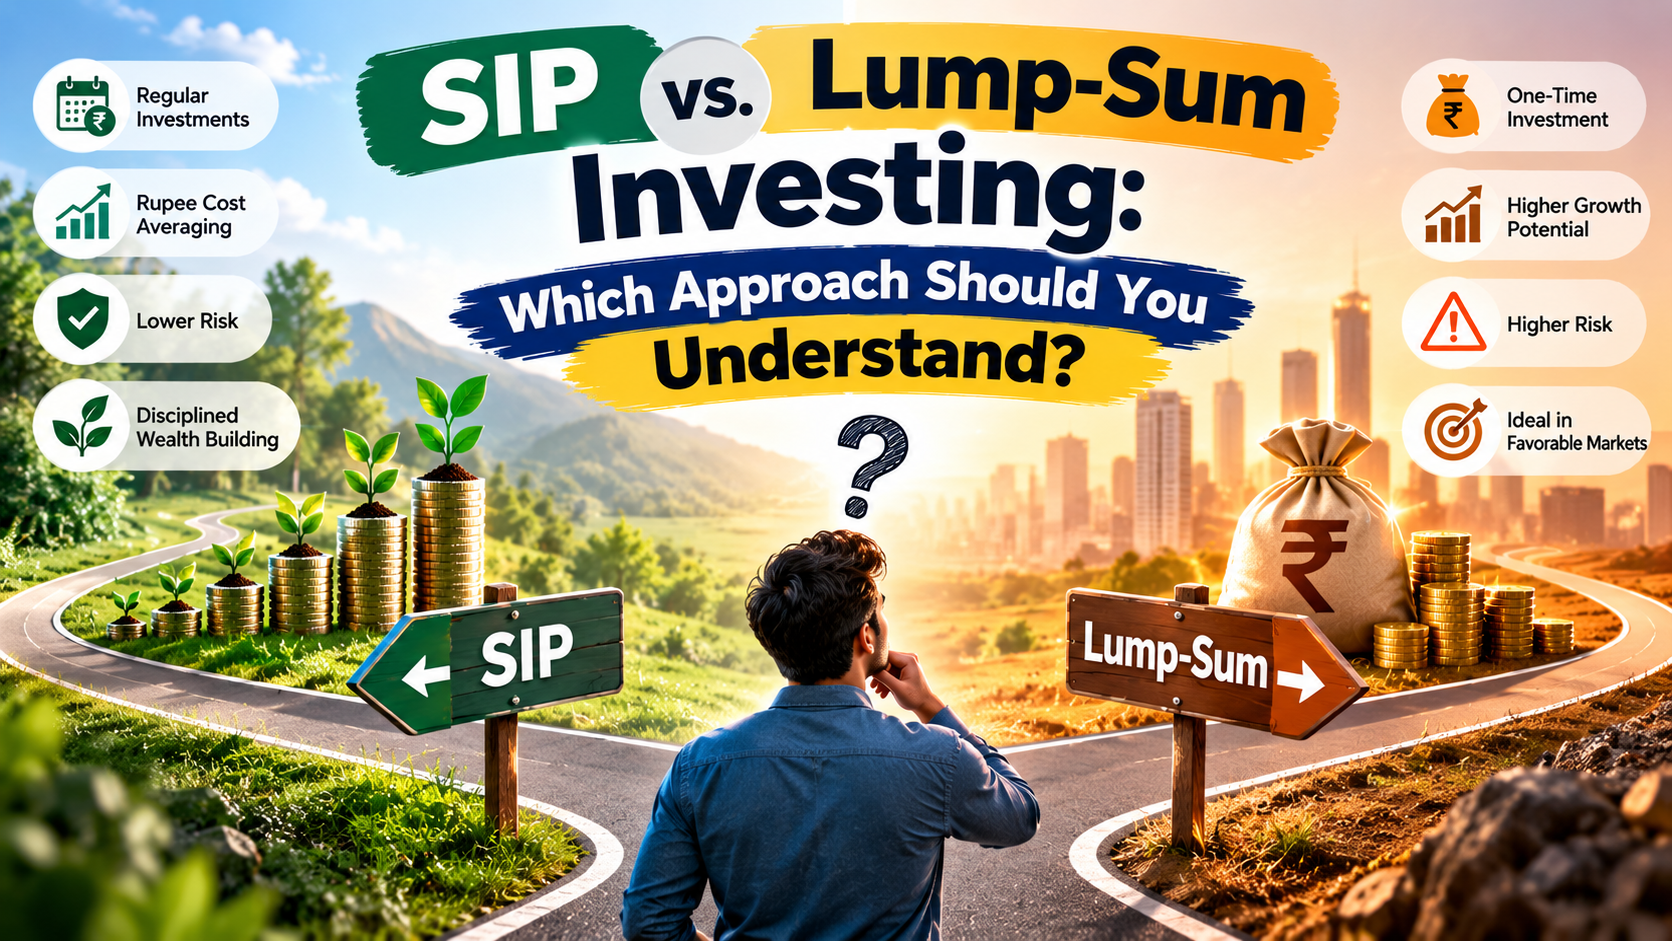
SIP vs. Lump-Sum Investing: Which Approach Should You Understand?
When investing in mutual funds, investors commonly choose between making regular contributions through a Systematic Investment Plan or investing a larger amount at one time.
Both methods can be useful, but they work differently.
The appropriate approach depends on factors such as when your money becomes available, your financial goals, your investment horizon, and your tolerance for market fluctuations.
What Is SIP Investing?
A Systematic Investment Plan allows you to invest a fixed amount at regular intervals.
For example, you might invest ₹5,000 every month into a mutual fund.
Each contribution purchases units at the applicable transaction NAV.
When the NAV is lower, the same contribution purchases more units. When the NAV is higher, it purchases fewer units.
This is commonly associated with rupee-cost averaging, although it does not guarantee profits or prevent losses.
SIPs can also help investors develop a consistent investing habit.
What Is Lump-Sum Investing?
Lump-sum investing involves investing a larger amount in one transaction.
For example, an investor who receives a ₹2,00,000 bonus might choose to invest some or all of that amount in a suitable investment.
The entire invested amount becomes exposed to market movements from the time of investment.
This can be advantageous when markets subsequently rise, but it can also result in significant losses if markets fall.
SIP vs. Lump-Sum Investing
Factor | SIP | Lump-Sum |
|---|---|---|
Contribution method | Regular installments | One larger investment |
Cash-flow suitability | Can suit regular income | Requires money available upfront |
Market exposure | Contributions enter over time | Entire amount enters at once |
Buying prices | Spread across multiple dates | Based on the transaction date |
Investment discipline | Encourages regular investing | Requires a decision about the available amount |
Return certainty | Not guaranteed | Not guaranteed |
Main consideration | Consistency and affordability | Timing, risk, and available capital |
Neither method guarantees better returns in every market condition.
Example: Investing ₹60,000
Suppose you have ₹60,000 available for investment.
You could invest the entire amount immediately or contribute ₹5,000 each month for 12 months.
The two approaches create different patterns of market exposure.
With lump-sum investing, the entire amount is invested from the beginning.
With a SIP, the money enters the market gradually as each contribution is made.
If prices rise consistently, investing earlier may provide greater exposure to those gains. If prices fall after the lump-sum investment, the immediate investment may experience a larger initial decline.
Actual results depend on market movements, transaction dates, fees, and the investment selected.
How Should You Choose?
Consider these questions before deciding.
1. Do You Have Money Available Now?
If you receive a substantial amount and have already set aside money for emergencies and near-term expenses, lump-sum investing may be worth evaluating.
If you earn a regular salary and invest from monthly income, a SIP may be more practical.
2. What Is Your Investment Horizon?
A longer horizon may provide more time to withstand market fluctuations, although it does not eliminate risk.
Money needed soon should generally not be exposed to substantial market volatility without careful consideration.
3. Can You Tolerate Market Declines?
Think about how you might react if your investment falls shortly after you invest.
Your ability to tolerate losses should influence the investment itself as well as the method used to contribute money.
4. Have You Established an Emergency Fund?
Before investing money that you may need unexpectedly, evaluate whether you have adequate emergency savings and sufficient funds for essential expenses.
Can You Combine Both Methods?
Yes. Some investors make an initial investment and then continue investing through regular contributions.
The suitability of this approach depends on their financial situation, investment objectives, and the product selected.
Avoid choosing a strategy based solely on predictions about short-term market movements.
Conclusion
SIP and lump-sum investing are different ways to allocate money to investments.
A SIP spreads contributions over time, while lump-sum investing puts the available amount to work immediately.
Understanding your cash flow, investment horizon, and risk tolerance can help you choose an approach that fits your financial plan.
Disclaimer: This article is for educational purposes only and does not recommend a particular investment method or mutual fund.